
Premium Bonds have never been more popular - but there are other some great alternatives for your money: Sarah Coles
Premium Bonds have just turned 70, and have never been more popular: there are 22 million people holding 138 billion bonds in the UK at the moment.
They’re a much-loved fixture on the savings landscape, and the savings tax hike announced in the Budget for next April is only going to strengthen people’s commitment to the chance of a tax-free prize. However, they come with a real downside, so it’s worth taking stock of whether they really deserve your affection, or whether there’s a better alternative.
Premium Bonds initially went on sale on 1 November 1956, with the first draw the following June. Things have changed significantly over the years -not least the fact that the jackpot has soared from £1,000 to £1 million. However, the basics remain the same.
It’s a savings product that lets you buy bonds worth £1 each – although there’s a minimum purchase of £25. You don’t earn any interest on these bonds. Instead, every month, every bond is entered into a prize draw, where you could win anything from £25 to £1 million. If you win, you get a prize and keep your bonds, and if you lose, you still keep your bonds and they’re entered into the next draw, and the one after that, and so on.
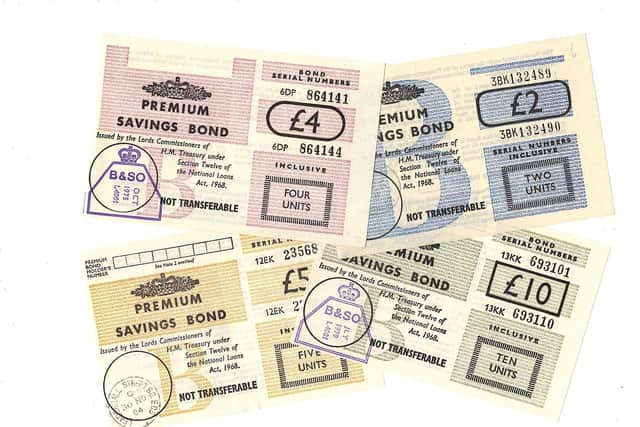

They appeal in huge part because people enjoy winning. It feels like a windfall, and that you’re getting something for nothing. However, in reality, instead of paying interest, that money is used to fund the prizes – so every bond holder is in fact funding prizes for other people. If you don’t win, it can feel like you haven’t lost anything, but the fact you’re not making any interest means your money will be losing spending power after inflation.
The prize rate is currently 4.35%, but if you have average luck, you won’t win prizes anywhere near as high as this rate. The fact that the lowest prize is £25, and there are some life changing sums on offer means the way prizes are distributed is massively uneven. It means in an average month, the average bond holder will win nothing. An AJ Bell Freedom of Information request found that nearly two-thirds (62%) of people have never won anything from their Premium Bonds, and those serial losers have held the bonds for an incredible 8.1 years on average.
It doesn’t mean that the bonds don’t have anything to offer. If you have large savings balances and average luck, you can win enough to keep pace with inflation. If you don’t pay tax on your savings, the typical return you get won’t compete with a top easy access savings account. However, things are a bit different if you've bust your savings allowance of £1,000 for basic rate taxpayers and £500 for higher rate taxpayers, because tax will eat into that return.
If you take a higher rate taxpayer, with £30,000 in a savings account paying 5%, they might earn £1,500 in interest in a year. However, £1,000 of it would be taxable, so they would only keep £1,100 of their interest. An additional rate taxpayer, meanwhile, would pay tax on all the interest, and keep £825. To make the equivalent return in a tax-free environment they would need an interest rate of 3.67% and 2.75%, which is a much lower bar.
Once the rate on savings tax is hiked by four percentage points in April next year, the higher rate tax would match 5% in a taxable environment with a tax-free return of 3.53% and the additional rate taxpayer with 3%. There are never any guarantees with Premium Bonds, but if you have £30,000 and average luck, this is possible. Of course, by the same token, you could win absolutely nothing. You need to be prepared for all eventualities when you buy Premium Bonds.
There are other tax-efficient alternatives worth considering, including the Cash ISA. Making the most of the £20,000 annual ISA allowance is an obvious first port of call. At the moment, the most competitive easy access cash ISA deals are actually more generous than their standard savings alternatives, so are well worth a look.
If you’re married, you can also consider moving income-producing assets from the higher-tax-paying individual to the lower-tax-paying spouse, so you can both use your cash ISA, and any excess can be charged at a lower rate of tax.
An interesting alternative is to invest in UK government bonds (which are also called gilts). The ones to watch for are the ones launched during the pandemic which are set to mature soon that offer a tiny income payment (known as the coupon).
The fact the income is so small doesn’t matter, because you’re interested in the capital gain. When they mature, you’re set to get back a specific sum – usually £100 per gilt – which is known as the redemption value. Repayment isn’t guaranteed, but would need the UK government to default on its debts before they fail to pay, so they’re considered relatively safe. The price you buy for will tend to be below the redemption price, so that’s how you make most of your money.
So, for example, you might get a bond priced at £90, with an income of 0.5%, which matures in two years. You’d get £1 of coupon payments over the two years, which would be subject to income tax, but because it’s such a small sum, you’re not losing much. Meanwhile, after the two years, it would mature and you’ll get £100 back – so you would have made £10 per gilt in capital gains, and all gains are free of CGT. It means an additional rate taxpayer might end up with a gain of £10.51 per gilt. Assuming all this happens after April next year, an additional rate taxpayer would need to make around 11% a year on a saving account to match it.
There are therefore some great alternatives to Premium Bonds, and some useful tax-efficient options. But for a lot of people, it doesn’t matter. They’ve held their Premium Bonds for decades, and they’re prepared to pay whatever price necessary for the chance of a life-changing win. As long as you understand what you’re missing out on, and what the alternatives have to offer, it’s completely up to you. Just try not to think too hard about the fact that the chance of any single bond willing the £1 million jackpot at the moment is around one in 2.7 billion.
Savings under pressure
The OBR forecast last week said it expects no growth in real earnings in 2027 and 2028, and that because energy prices are set to soar, real household disposable income will fall slightly in the near term. It will push some households to save less, some to eat into their savings and others to build up debts.
With this looming on the horizon, it’s worth taking stock of how robust your emergency savings safety net is. As a rule of thumb, while we’re working, we should be working towards enough emergency savings to cover 3-6 months’ worth of essential spending – rising to 1-3 years’ worth in retirement.
If you’re falling short, it’s not worth waiting until your finances are in better shape before you get started, because money is going to get tighter before things get better, so it’s worth taking steps to beef up your emergency savings before life gets more expensive.