
Phil Spencer on why Yorkshire first-time buyers are changing where and how they buy
Phil Spencer still remembers the deal that got him onto the property ladder. It was 1997 in Battersea, then an unfashionable part of London, and far from a conventional first purchase.

“It wasn't a place that I would have particularly chosen to live at the time but I did see an opportunity through a friend,” he says. “I bought it for £160,000 and I'll never do a better deal in my life. I struck it lucky.”
Nearly three decades on, the Location, Location, Location presenter acknowledges that today’s first-time buyers face a very different landscape, defined by affordability pressures, rising borrowing costs and market uncertainty.
Property Post caught up with Phil during his visit to Yorkshire as part of Move iQ’s partnership with Skipton Building Society. The founder of the property advice platform was speaking to Skipton staff about the challenges facing today’s house buyers. Alongside him was Charlotte Harrison, chief executive of home financing at Skipton.
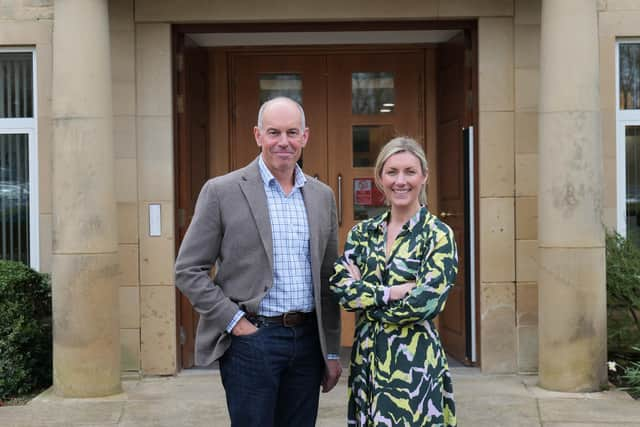

The pair say hesitation has become a defining feature of the property market where affordability varies sharply by area. According to Skipton’s latest Home Affordability Index, Hull ranks 74th out of 363 local authorities nationally, with 18 per cent of households able to afford a first step onto the ladder.
In contrast, Hambleton in North Yorkshire sits near the bottom at 362nd, with just five per cent able to do so, while York (seven per cent), Scarborough (nine per cent) and Sheffield (10 per cent) also rank among the least affordable in the region.
Recent data shows that pressures are intensifying. More than 200 mortgage deals for buyers with a five per cent deposit have been withdrawn since early March, according to Moneyfactscompare.co.uk, as lenders respond to volatility in swap rates and changing expectations around interest rates. Average two-year fixed rates at high loan-to-value levels have climbed above six per cent, adding significantly to borrowing costs.
For many buyers, particularly those relying on a single income, the challenge is stark.Yet both Phil and Charlotte emphasise that solutions do exist - albeit requiring flexibility.
“Buyers everywhere have to find where they can afford the space that they need, and it's very unlikely to be in an area that's their pick of the bunch,” Phil says. “You might have to travel a bit further, or consider areas that you hadn't in the past.”
Charlotte highlights hybrid working as a key factor supporting this shift. “Our affordability index shows that first time buyers are buying better quality, slightly larger homes but not necessarily in their favourite location,” she says. “If you've only got to be in the office two days, suddenly an hour commute is more appealing.”
That increased flexibility is widening the search area for buyers, bringing more of the region into play. “Yorkshire is such a beautiful county. It's such a big county, and it's such a varied county. It offers an awful lot of things at different price points,” Phil says.
Charlotte identifies two core challenges for first time buyers: raising a deposit and stretching borrowing capacity. In response, lenders are increasingly developing products aimed at bridging the gap.
Skipton’s Track Record mortgage offers up to 100 per cent loan to value with a track record of paying rent, to help buy a home. Other products, such as shared ownership and income-boosting mortgages involving family members, are also playing a role.
Beyond first-time buyers, both Phil and Charlotte highlight growing pressures further up the ladder. A widening gap between first and second moves is emerging, driven in part by higher mortgage rates and transaction costs.
“If I could change one thing it would be stamp duty,” Charlotte says. “It makes it prohibitive for people to move.”
Phil agrees, pointing to a lack of mobility across the market.
According to Savills, owner-occupiers aged 60 and over hold the majority of the UK's net housing wealth in the UK.
“There are 10 million empty beds in this country but there’s no motivation for people to downsize,” Phil says.
He argues that constraints at both ends of the market - from first-time buyers struggling to save, to older homeowners staying put -are reducing overall supply and pushing up costs, particularly in the rental sector.
Against this backdrop, both emphasise the importance of preparation and research for would-be buyers. “These are big decisions. You want to take them with as much confidence as you possibly can,” says Phil.
Charlotte adds that buyers should focus less on how much they can borrow and more on long-term affordability. “The question they really need to be asking is, how much do I want to spend every month?”
For those navigating Yorkshire’s market today, Phil believes strategy is key. Sellers, he says, must be realistic on price, while buyers are currently in a stronger negotiating position. “Buyers are in the powerful seat so you can negotiate hard. This is not the time to accept too many compromises,” he says.